Military & VA homebuyers
Active-Duty Military & Veterans: You May Be Able to Buy a Home With $0 Out of Pocket.
If you've wanted to buy but held off because of interest rates, home prices, or upfront costs, let's explore what may be possible with VA financing and a well-negotiated purchase.
What may be possible
- $0 down payment for eligible buyersWhen the price doesn't exceed the VA appraised value and the lender approves the loan.
- Potentially $0 out-of-pocket closing costsSellers can credit closing costs. The VA funding fee can be financed, or you may be exempt.
- Opportunities to negotiate below askingDepends on the home, the competition, and the seller.
- Seller-paid rate buydown optionsSubject to lender approval and applicable VA rules.
Eligibility, lender approval, property requirements, and negotiated terms apply. Zero-out-of-pocket purchases are possible but not guaranteed.
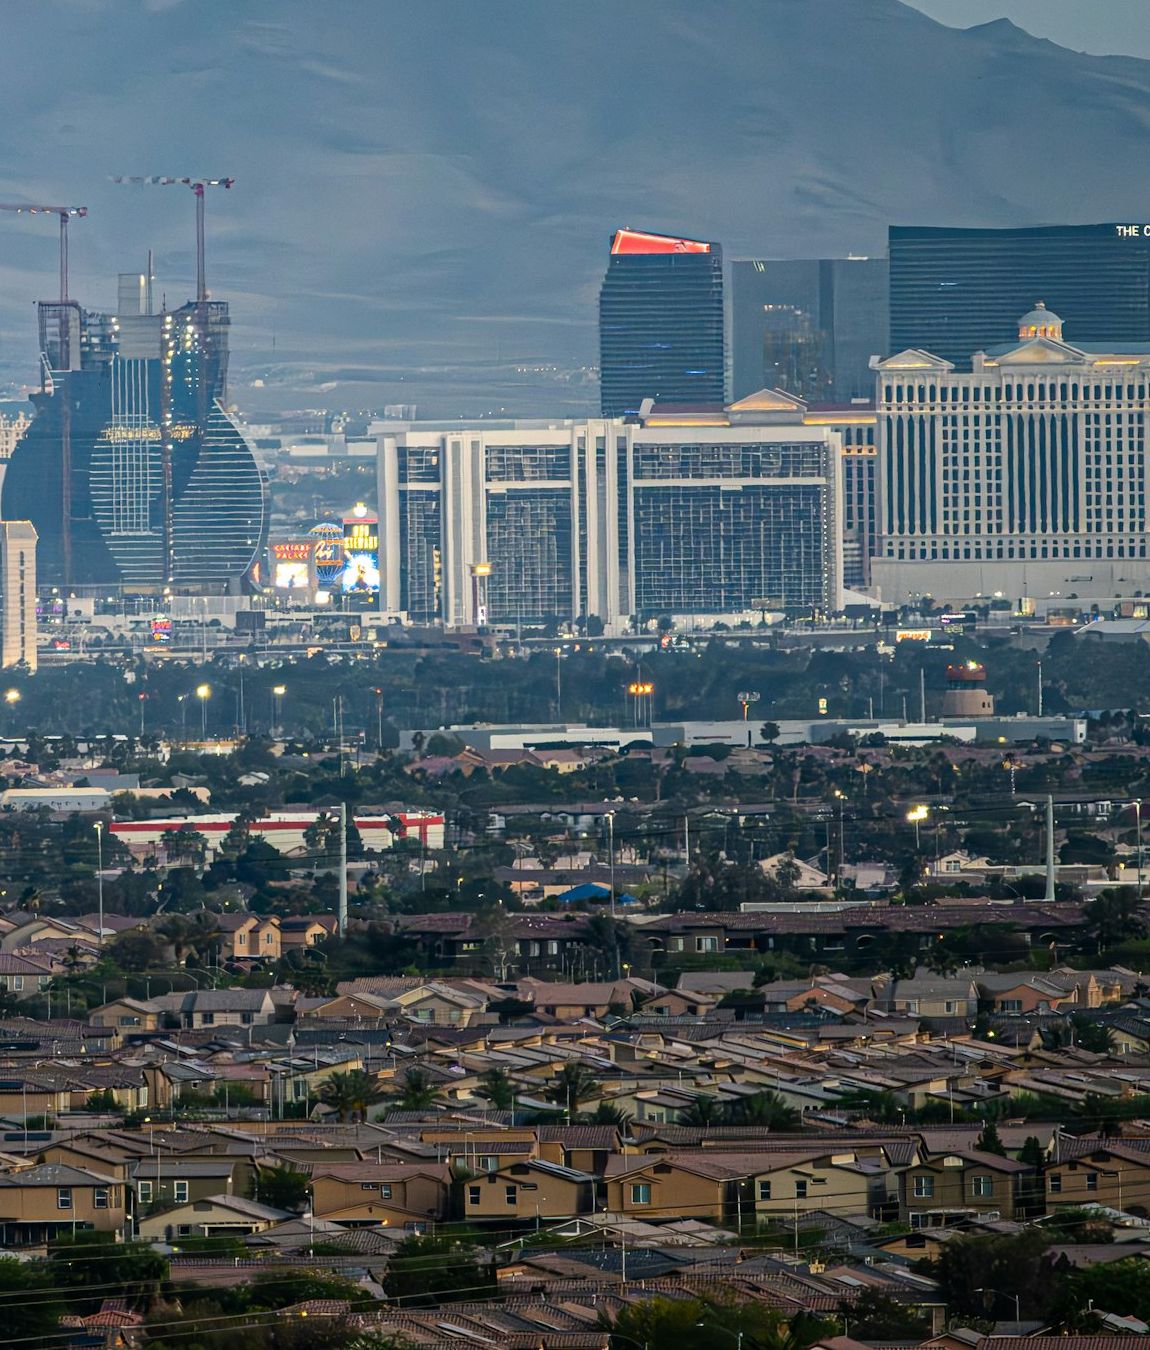
Las Vegas, Nevada. Photo by Tyler Hardie on Unsplash.
Why negotiation matters
More Room to Negotiate. More Ways to Preserve Your Cash.
When a home has less competition or a motivated seller, a qualified buyer may be able to negotiate more than the price. That depends on the property and the seller, so I look at each home on its own and tell you what I see, including when there isn't room.
Purchase price
Listing history, days on market, and comparable sales show whether the asking price has room in it.
Seller-paid closing costs
VA allows sellers to credit some or all of your closing costs. The credit is negotiated in the contract.
Mortgage rate buydowns
A seller can fund a buydown that lowers your rate or payment. Seller-funded temporary buydowns count toward VA's 4% concession limit.
Other favorable terms
Closing date, repairs, inspection timing, and earnest money are contract terms, and each one can be negotiated.
Buyer negotiation example
A Real Negotiation: $60,000 Below Asking, Plus $20,000 in Seller Concessions.
An initial $430,000 offer opened negotiations on a property listed at $520,000. The accepted agreement was $460,000, with an additional $20,000 in seller concessions.
This is one of my buyer clients' purchases, shown here as an example of negotiation. It isn't presented as a VA-financed sale.
See more buyer negotiations- Original asking price
- $520,000
- Initial offer
- $430,000
- Accepted purchase price
- $460,000
$60,000
Reduction from asking
Asking price minus accepted price
$20,000
Seller concessions
Separate from the purchase price
Combined price reduction and seller concessions
$80,000
In this transaction, the seller concessions also helped reduce the buyer's mortgage rate from nearly 7% to approximately 5.9%. The buydown structure and duration are not specified here. This historical example is not a current rate offer.
Personal experience
Helping Military Families Become Homeowners Since 2012.
I started helping active-duty service members and veterans buy homes in 2012. Early in my career, I regularly visited Nellis Air Force Base and spoke with service members about their homebuying options.
Since then, I've helped eligible VA buyers complete purchases with no down payment, no out-of-pocket closing costs, no upfront appraisal payment, and no upfront earnest money. Each of those came from a specific transaction and a negotiated contract. They aren't automatic VA benefits or a guarantee, but they show what's possible when the loan and the negotiation work together.
Past results for eligible VA buyers
- No down payment
- No out-of-pocket closing costs
- No upfront appraisal payment
- No upfront earnest money
My career
- years in real estate
- 16+years in real estate
- career transactions
- 1,000+career transactions
- in career sales
- $150M+in career sales
- licensed in Nevada and Florida
- NV & FLlicensed in Nevada and Florida
Career figures cover all of my real estate work, not VA purchases alone.
How it works
Four steps from first question to closing.
My goal is to help you keep more of your cash while negotiating favorable terms. The lender makes the financing and preapproval decisions. I make sure the offer fits the loan.
- 1Tell Me About Your GoalsShare your preferred area, timing, and questions.
- 2Review Financing With a VA LenderI can coordinate an introduction to a qualified lender who reviews eligibility, financing, and estimated costs.
- 3Identify Homes With Negotiating PotentialWe evaluate suitable properties, pricing, competition, days on market, and what's known about the seller's motivation.
- 4Negotiate the Whole PurchaseWe work toward a favorable price, eligible seller credits, closing costs, and potential buydown terms.
Service areas
Buying in Nevada, in Florida, or relocating with the military.
Nevada
Las Vegas, Henderson, North Las Vegas, Summerlin, Spring Valley, Mountain’s Edge, and Reno, plus other Nevada areas I can serve well. I'll tell you if another agent would serve you better.
Florida
I'm licensed in Florida and work with buyers there through my license and professional network. Tell me the city, and I'll explain how I can help.
Other states
I'm licensed only in Nevada and Florida. If you're buying somewhere else, I may be able to help coordinate a referral to an agent licensed in that state.
Find Out What's Possible With Your VA Benefits.
No pressure. No obligation. Tell me a little about your plans, and I'll personally follow up to help you explore your options.
- Takes about two minutes. Email is enough to start.
- No documents, Social Security numbers, or service records.
- A lender, not this form, reviews eligibility and preapproval.
VA homebuying questions.
Can a VA loan allow no down payment?
Yes, for eligible buyers. VA doesn't require a down payment as long as the sales price isn't higher than the home's appraised value and the lender approves the loan. If you have full entitlement, VA sets no loan limit, though the lender still decides how much you qualify for. If part of your entitlement is tied up in another VA loan, a higher-priced purchase may need some money down.
Can sellers pay closing costs?
Yes. VA allows sellers to give credits that cover some or all of a buyer's closing costs, and it doesn't limit those closing-cost credits. Seller concessions are a separate category: extras such as paying your VA funding fee, prepaying your hazard insurance, paying off a debt for you, or funding a temporary buydown. VA caps concessions at 4% of the home's reasonable value from the VA appraisal. Your lender confirms how each credit is classified.
Is an appraisal still required, and who pays?
Yes. A VA-approved appraiser values the home and checks basic property condition requirements. It isn't a home inspection, so an inspection is still worth considering. The VA appraisal fee is a closing cost that the buyer and seller can negotiate, and the lender decides when it's collected. If the appraisal comes in below the price, you can ask for a reconsideration, renegotiate, or pay the difference.
Is earnest money required?
Earnest money is set by the purchase contract between you and the seller, not by the VA loan program. Many sellers expect a deposit, and the amount and timing are negotiable. I've helped VA buyers complete purchases with no upfront earnest money, but that depends on the seller and the contract.
Can seller credits help with a rate buydown?
Yes, within VA's rules. VA allows temporary buydowns on fixed-rate VA loans, and the seller can fund them. A seller-funded temporary buydown counts toward the 4% concession limit, and the lender still qualifies you at the full payment that applies after the buydown ends. Sellers can also pay discount points to lower the rate for the life of the loan; your lender will confirm how those are counted.
Can VA benefits be used more than once?
Yes. You can use the benefit again after you sell or refinance a home bought with a VA loan. Entitlement can be restored when the prior loan is paid off and the home is sold, when a qualified veteran assumes the loan, or one time if you pay off the loan and keep the home. The VA funding fee is usually higher after first use: 3.3% instead of 2.15% with less than 5% down, unless you're exempt.
Can someone use VA financing while already owning a home?
Often, yes. Owning a home doesn't rule out VA financing on its own. The home you're buying must be the one you'll live in, and if your current home has a VA loan, you may still have remaining entitlement for another purchase. Your Certificate of Eligibility shows entitlement already in use, and the lender works out what's available.
Can active-duty buyers purchase a home?
Yes. Service members generally qualify after 90 continuous days of active service. If your duty keeps you from living in the home, the occupancy requirement can be met by your spouse, or by a dependent child with the certification made by your attorney-in-fact or the child's legal guardian. That can help when you're buying ahead of a military move.
Do I need preapproval before contacting Aaron?
No. Many buyers reach out before they talk with a lender. With your permission, I can introduce you to a qualified VA lender, who reviews eligibility, preapproval, and estimated costs. I don't send your information to a lender unless you ask me to.
Which areas does Aaron serve?
In Nevada: Las Vegas, Henderson, North Las Vegas, Summerlin, Spring Valley, Mountain’s Edge, Reno, and other areas I can serve well. In Florida, I work through my Florida license and professional network. I'm licensed only in Nevada and Florida; for another state, I may be able to help coordinate a referral to a licensed agent there.
VA rules summarized from VA purchase loans, VA funding fee and closing costs, VA temporary buydowns, VA eligibility, VA entitlement and loan limits, the VA home buying process, and 38 U.S.C. § 3704(c), reviewed October 2026. Your lender confirms how they apply to you.
Aaron Mazza is a real estate agent, not a mortgage lender. VA eligibility, lender approval, property requirements, and transaction terms apply. Zero-out-of-pocket purchases are possible but not guaranteed. This website is not affiliated with or endorsed by the U.S. Department of Veterans Affairs or the U.S. military.